How starter-interrupt and GPS kill switch devices work and who can legally use them
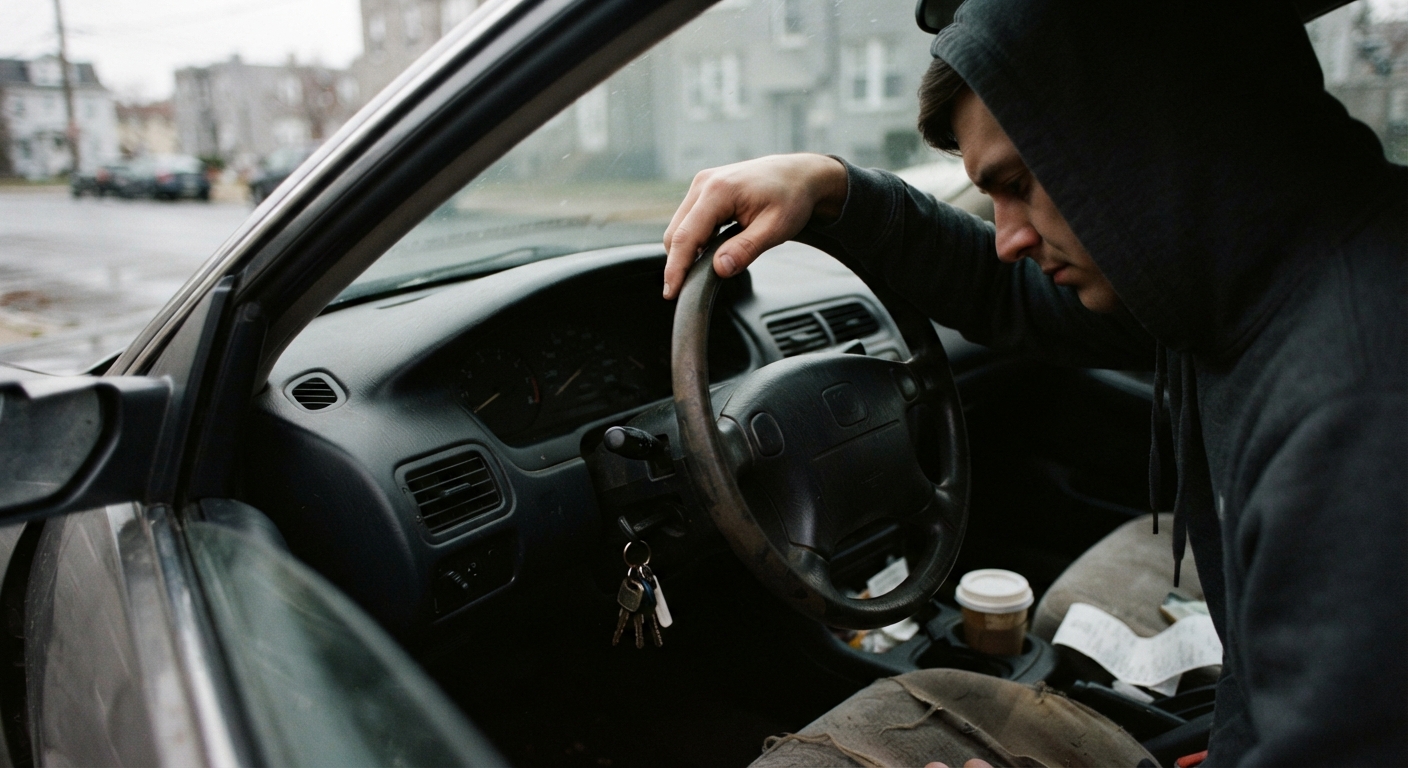
A starter-interrupt device is a small module wired into your car’s ignition or starter circuit, usually installed at the dealership when the loan was signed. It doesn’t cut your engine while you’re driving on the highway. Instead, it blocks the car from starting the next time you turn the key off, which is why these devices almost always trigger when you’re parked — outside work, at home, in a store lot.
Some devices are paired with GPS tracking, which lenders use to locate the vehicle if it needs to be repossessed. Others are simpler and only handle the disable function. Either way, the device is controlled remotely by the lender or a third-party servicing company, and it’s typically activated after a missed payment, usually following at least one text or automated call warning that the loan is behind.
Lenders who use these devices are legally allowed to disable a car you’re not fully paying for — the vehicle is collateral until the loan is paid off. What lenders are generally not allowed to do is disable the car in a way that creates a dangerous situation, such as while it’s in motion, or without disclosing at the time of the loan that the device exists. That disclosure question matters a lot, and it’s the next thing to check.
Checking your loan agreement for disclosure of a disable device
Pull out your loan contract, retail installment agreement, or any paperwork you signed at the dealership. Look specifically for language about a “starter interrupt device,” “payment assurance device,” “GPS device,” or “collateral protection technology.” Many contracts disclose this in a separate paragraph or addendum you initialed.
If you can’t find your paperwork, call the lender and ask directly whether a disable device was disclosed in writing and where in the contract it appears. Ask them to send you a copy of that page. You’re not asking for a favor — you’re entitled to a copy of your own loan agreement.
If the device isn’t mentioned anywhere in your paperwork, write down the date you noticed that, along with who you spoke to at the lender and what they said. This becomes relevant if you later decide to dispute the disable action or file a complaint with a state regulator.
Immediate steps if you’re stranded somewhere unsafe when it triggers
If the car dies somewhere that doesn’t feel safe — a dark lot, a highway shoulder, an unfamiliar area at night — your safety comes first, before any call to the lender. Move away from traffic, lock the doors, and call a friend, family member, or rideshare to get you somewhere safe if you can’t wait it out in the car.
Once you’re safe, here’s the order that gets you moving fastest:
1. Check your phone for the text or call that mentioned the loan. Save it — you’ll need the reference number or account info when you call back.
2. Call the number in that message, or the main customer service line on your loan statement. Tell them exactly where the car is and that it won’t start.
3. Ask directly: “Was this car disabled remotely, and can it be re-enabled today?” Lenders can usually reverse the disable within minutes to hours once a payment arrangement is confirmed.
4. If you have someone who can sit with you or bring supplies while you wait, especially in extreme heat or cold, call them next.
Don’t try to bypass or disconnect the device yourself. Tampering with it can violate your loan agreement and may cause additional fees or an immediate repossession action.
Calling the lender to negotiate a re-enable in exchange for a partial payment
Most lenders using these devices want one thing: money moving again. That gives you leverage even if you can’t pay the full past-due amount right now.
When you call, be specific and calm. Say what you can pay today, ask what amount triggers a re-enable, and ask if a partial payment plus a promise date for the rest will get the car working again. Many servicers will reactivate the vehicle for a partial payment, especially if you have a history of paying on time before this.
Get everything in writing or a confirmation number, including the exact amount you agreed to pay, the date the car will be re-enabled, and what happens if the remaining balance isn’t paid by the promised date. Ask how long the re-enable will last — some devices are set for a grace window and will disable again automatically if a follow-up payment doesn’t post.
If the representative says they can’t reactivate it without a full payment, ask to speak with a supervisor or the loss mitigation department specifically. Front-line reps sometimes have less authority to approve partial payment arrangements than the escalation team does.
What happens if the car is towed instead of just disabled
Disabling and repossessing are two different actions, and a disabled car can still be towed if the lender decides to move to repossession instead of waiting for payment. If you come back to find the car simply gone rather than dead in place, that’s a repossession, not a kill switch event.
If this happens, call the lender immediately to find out which tow yard or storage facility has the vehicle. Ask what it will cost to redeem the car — meaning pay what’s owed plus repossession fees to get it back — and how many days you have before it’s sold at auction. Ask specifically whether personal belongings left inside the car are still accessible, and how to retrieve them even if you can’t redeem the vehicle itself.
Every day matters here. Storage fees typically accrue daily, and the window to redeem a repossessed vehicle before it’s sold is often short.
Your rights if the lender didn’t give required notice before disabling the vehicle
Depending on where you live, lenders using disable devices are often required to give some form of notice before triggering one — a text, a call, or a letter — rather than shutting the car down with zero warning. If you received no warning at all before the car failed to start, ask the lender directly what notice was sent, when, and to what phone number or address.
If the answer is vague, or the notice went to an old phone number you no longer use, say so and ask them to note it on your account. Keep a record of the date and time you called, who you spoke with, and what they told you about their notice policy.
If you believe the lender skipped a required notice step, you can file a complaint with your state’s attorney general consumer protection office or a financial regulator that oversees auto lenders in your state. A complaint doesn’t guarantee a specific outcome, but it creates a paper trail and can prompt the lender to review the account. If the situation feels tangled — repeated disables, disputed fees, or a repossession you think was improper — a consumer law attorney or your local legal aid office can look at the specific facts of your loan and tell you what options actually apply to your situation.