Why a debt lawsuit summons is not the same as a collection letter
If you’ve been dealing with a collection agency, you’re probably used to letters and phone calls. Those are annoying, but they don’t have a legal deadline attached to them. A summons is different. It means someone has actually filed a lawsuit against you in court, and the court is now involved. That single fact changes everything about how you need to respond.
A collection letter asks you to pay. A summons tells you that you are being sued, names the court where the case was filed, and gives you a fixed number of days to file a written response, called an answer. If you treat a summons like just another piece of collection mail and set it aside, you can lose the case automatically without ever saying a word in your own defense. That’s not a scare tactic, it’s just how civil court procedure works. The court assumes that if you don’t respond, you don’t dispute what’s being claimed.
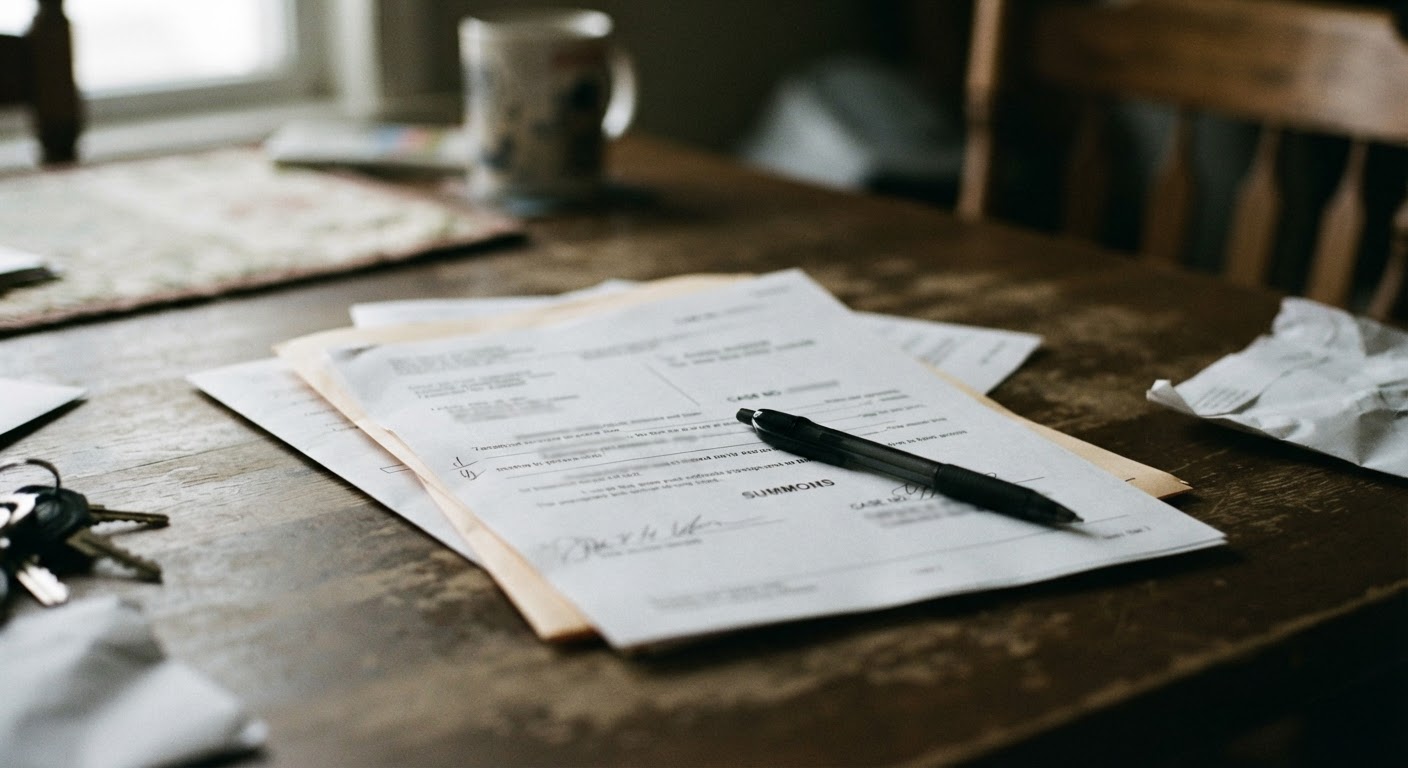
This is why the very first thing to do when you’re served with a lawsuit is confirm what kind of document you’re actually holding. Look for words like “Summons,” “Complaint,” “Civil Action,” or a case number and court name at the top. If you see those, you are past the collection-letter stage and into a legal proceeding with a clock already running.
Finding your response deadline on the summons itself
The summons itself will almost always state your deadline directly. Look near the top or in the first paragraph for language like “you must respond within” a certain number of days, or “you are required to appear or answer by” a specific date. Courts commonly use a set number of calendar days from the date you were personally served, though the exact number varies depending on where you live and how you were served, so don’t assume it matches what happened to a friend or relative in a different state.
A few details matter when you’re reading the summons:
The clock usually starts on the date you were served, not the date on the document or the date you happened to open the envelope. If someone else accepted the papers for you, or they were left at your door, that date still counts. Weekends and holidays typically count toward the deadline too, unless the deadline itself lands on one, in which case it may roll to the next business day.
If the summons doesn’t clearly state a number of days, look for the name of the court at the top of the page. Every court has published local rules that state the standard answer deadline for civil cases, and the clerk’s office can tell you the deadline for your specific case type over the phone. Don’t guess. Call and ask directly, and write down the date you’re given along with the name of the person who told you.
Mark the deadline somewhere you will absolutely see it every day. Not just in a calendar app, but on paper, on the fridge, wherever you look daily. These deadlines are short, often just a couple of weeks, and there is no cushion built in for confusion or delay.
What happens if you miss the deadline: default judgment
If you don’t file an answer by the deadline, the person or company suing you can ask the court for a default judgment. This means the court rules in their favor automatically, without a hearing on the merits, simply because you didn’t respond in time. Once that judgment is entered, it carries the same weight as if a judge had heard the whole case and ruled against you.
A default judgment can lead to wage garnishment, a lien on property, or a levy on a bank account, depending on what’s allowed where you live. It also becomes part of the public record and can affect your credit standing for years. Reversing a default judgment after the fact is possible in some situations, but it typically requires filing a separate motion, explaining to the court why you missed the deadline, and convincing a judge to give you another chance. That process is harder, slower, and less certain than simply filing your answer on time in the first place.
If you’re staring down a deadline that’s only days away, the priority is getting something filed before that date, even if it’s not perfect. A basic, timely answer keeps the case alive and preserves your right to be heard. Missing the date closes that door.
What a basic written answer needs to include
An answer doesn’t need to be long or written in legal language. At its core, it’s a written response to the complaint that was filed against you, addressing each claim the plaintiff made. Most court systems provide a fill-in-the-blank answer form for debt collection cases specifically, and using that form, if one is available, is usually the simplest path.
Your answer generally needs to include the case number and court name exactly as they appear on the summons, your name and contact information, and a response to each numbered claim in the complaint. For each claim, you typically state whether you admit it, deny it, or don’t have enough information to admit or deny it. You don’t need to explain your reasoning in detail at this stage, you just need to respond to each point.
Your answer should also list any defenses you intend to raise, even briefly. Courts generally require you to state defenses somewhere in your written response or risk losing the ability to raise them later. Once the form is complete, it needs to be filed with the court clerk by the deadline, and in most cases you’re also required to send a copy to the plaintiff or their attorney. Ask the clerk about the exact filing and service steps for your court, since these procedural details vary by jurisdiction.
Common defenses worth raising even without a lawyer
You don’t need to be a legal expert to raise legitimate questions about a debt lawsuit. Some of the most common issues worth stating in your answer include whether the amount claimed is actually correct, whether the debt is too old to be legally collected through a lawsuit where you live, and whether the company suing you actually owns the debt or has proof that it does.
Debt is often sold and resold between collection companies, and paperwork gaps are common. It’s reasonable to state in your answer that you dispute the amount owed or that you demand proof the plaintiff has the right to collect this specific debt. You can also state that you were never properly served, if that’s true, or that the debt belongs to someone else entirely, such as a case of mistaken identity or identity theft.
Raising these points doesn’t guarantee a particular outcome, but it keeps your options open and often prompts the other side to actually produce documentation, which sometimes changes the course of the case.
Where to get free or low-cost help filing your answer in time
Court clerks cannot give legal advice, but they can tell you deadlines, point you to the correct answer form, and explain filing procedures. Start there immediately if you haven’t already.
Legal aid organizations in most areas offer free help specifically for debt collection lawsuits, often including same-day phone consultations or walk-in clinics for people facing a fast-approaching deadline. Law school legal clinics, local bar association referral lines, and self-help centers attached to many courthouses can also help you complete and file an answer quickly. If you’re working with a caseworker or shelter staff member, ask them to help you locate the nearest legal aid intake line today rather than waiting, since some of these services have their own scheduling delays.