What a Default Notice Actually Means Versus Late Payment Reminders
A late payment reminder is a nudge. A notice of default is a legal marker. The two look similar on paper — both mention a missed payment and a dollar amount owed — but they trigger very different clocks. A reminder usually shows up after one missed due date and asks you to pay soon to avoid a fee. A default notice means the creditor has determined, under the terms of your original credit agreement, that you’ve breached the contract seriously enough to move toward the next stage of collection.
Read the notice itself, not just the envelope. Look for language like “notice of default,” “right to cure,” or “acceleration.” Those phrases mean the creditor is telling you exactly how many days you have to fix the problem before it takes further action, which might include reporting the account as charged off, accelerating the full balance (demanding the entire remaining amount instead of just the missed payment), or referring the account to collections.
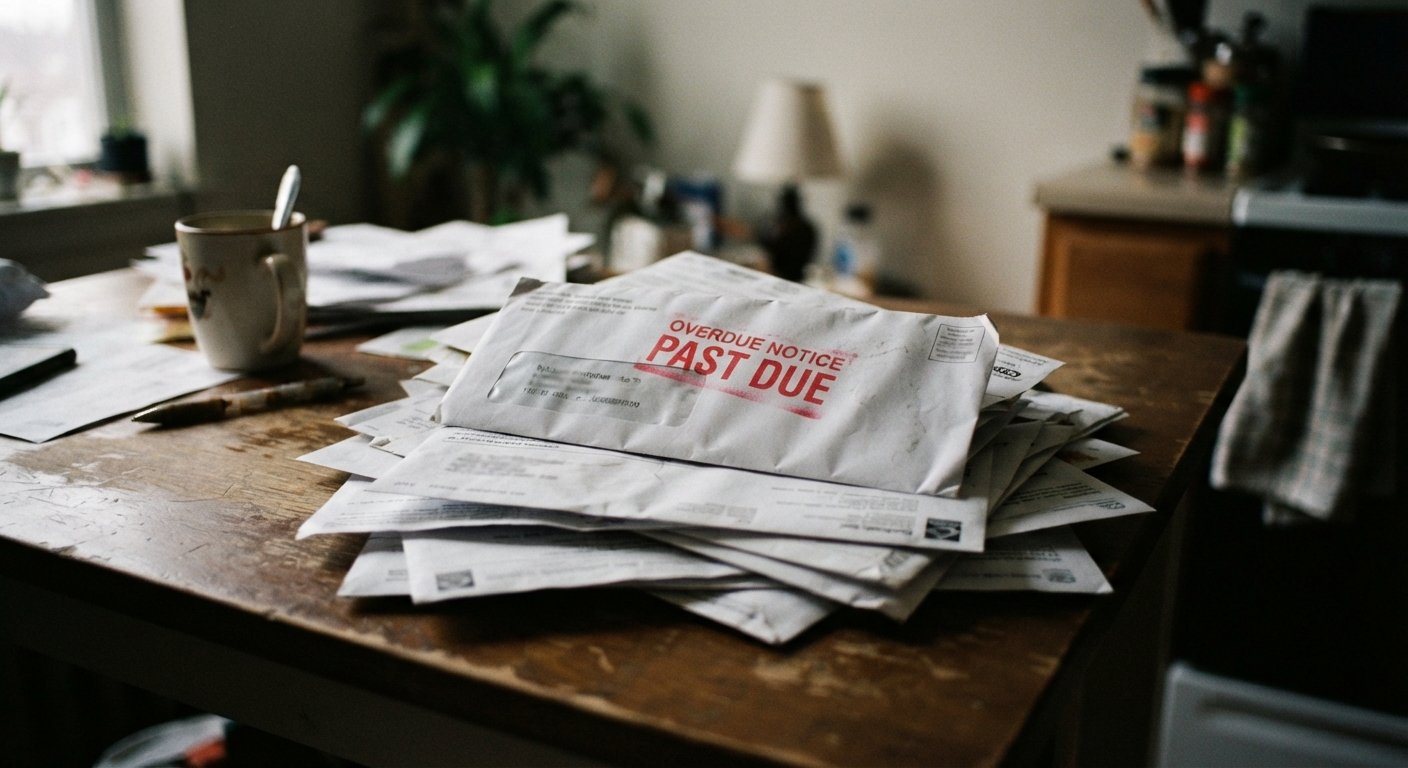
If the letter only says “payment past due” or “your account is delinquent,” you’re likely still in the early-warning phase. That’s a real difference worth knowing, because it changes how urgently you need to act and who you should be talking to first.
Typical Day Counts Before a Creditor Charges Off the Account
Most credit card issuers and personal loan servicers follow a similar internal timeline, even though the exact wording in your agreement controls what actually applies to you. A payment is typically considered late the day after the due date, but it usually doesn’t get reported to credit bureaus as delinquent until it’s 30 days past due. From there, many creditors send default notices somewhere between 60 and 90 days of missed payments, once the account has clearly moved past a one-time slip.
Charge-off — the point where the creditor writes the debt off as a loss on their books — commonly happens around 180 days of nonpayment for credit cards. Personal loans can vary more, since some lenders charge off sooner and some wait longer, depending on the size of the loan and their internal policy. The number that matters most isn’t a general industry average — it’s the specific day count printed in your notice. If the letter says you have 30 days to cure the default, that’s the number to plan around, not 180.
Check the notice for a stated deadline. If there isn’t one, call the creditor and ask directly: “What day does this account get charged off or sent to collections if I don’t pay?” Get the date in writing if you can, even a follow-up email confirming what a representative told you on the phone.
How Charge-Off Timing Affects Your Credit Report and Future Collection Calls
Charge-off doesn’t mean the debt disappears. It means the original creditor has stopped treating it as an active account they expect to collect on themselves, and it often shifts the account into a different phase: either an internal collections unit, a third-party collection agency, or a sale to a debt buyer. Each of those has its own contact process, and each restart can feel like starting over with someone new who doesn’t have the history you’ve built with the original lender.
Once charged off, the account is typically reported to credit bureaus as a charge-off, which is a serious mark that can affect your credit for years. The debt itself doesn’t vanish — you still owe it — but who you owe it to and who’s calling you about it can change quickly once this happens. That’s part of why the period before charge-off matters so much: it’s often your best window to deal with one entity you already have a relationship with, rather than a rotating cast of collectors later.
If you start getting calls from a new company name after previously dealing only with your original bank or lender, that’s usually a sign the account has already moved. It doesn’t mean you’ve lost all options, but it does mean the conversation has shifted from “can we work something out” to “let’s figure out what’s now owed and to whom.”
Your Options to Cure the Default Before It’s Sold to a Collector
Curing a default generally means bringing the account current — paying the missed amount, plus any fees, before the deadline stated in the notice. That’s the cleanest fix if you have or can gather the money. But full payment isn’t the only path, and creditors often have more flexibility than the notice implies.
Common options worth asking about directly:
A partial payment plan that spreads the past-due amount over the next several billing cycles instead of requiring it all at once. A temporary hardship program, which some credit card issuers and lenders offer to people dealing with job loss, medical issues, or other short-term disruptions — these can include reduced interest or paused payments for a set period. A settlement offer, where you propose paying a portion of the balance as payment in full, which creditors sometimes accept before charge-off because it’s cheaper for them than selling the debt to a collector for cents on the dollar. Refinancing or consolidating the debt into a new loan with different terms, though this depends on your credit standing at the time.
Whatever you’re offered, get it in writing before you send money. Verbal promises from a phone representative are hard to enforce later if the account still gets reported as defaulted despite your payment.
When to Negotiate Directly With the Original Creditor Versus Waiting
The single biggest advantage you have is time before charge-off. Once the debt is sold or assigned to a collector, you lose the ability to negotiate with someone who has full history on your account and more institutional flexibility to adjust terms. Original creditors also have more reason to keep you as a customer, which can make them more willing to work with you than a collection agency that only profits if you pay something toward the debt they purchased.
Call the original creditor as soon as you get a default notice, even if you can’t pay anything yet. Ask what cure options exist, whether hardship programs are available, and what the exact deadline is before the account moves to another stage. Don’t wait for a “better time” to call — creditors’ willingness to negotiate tends to shrink the closer you get to their internal charge-off date, not grow.
Waiting only makes sense in one scenario: if you’re expecting a specific, verifiable payment source within days — a paycheck, a settlement, a tax refund already filed — and that date falls before the notice deadline. Even then, call first and explain the timing. Creditors can sometimes extend a deadline by a short window if they believe payment is genuinely coming and you’ve been upfront about it. Silence, on the other hand, almost always accelerates the timeline rather than pausing it.