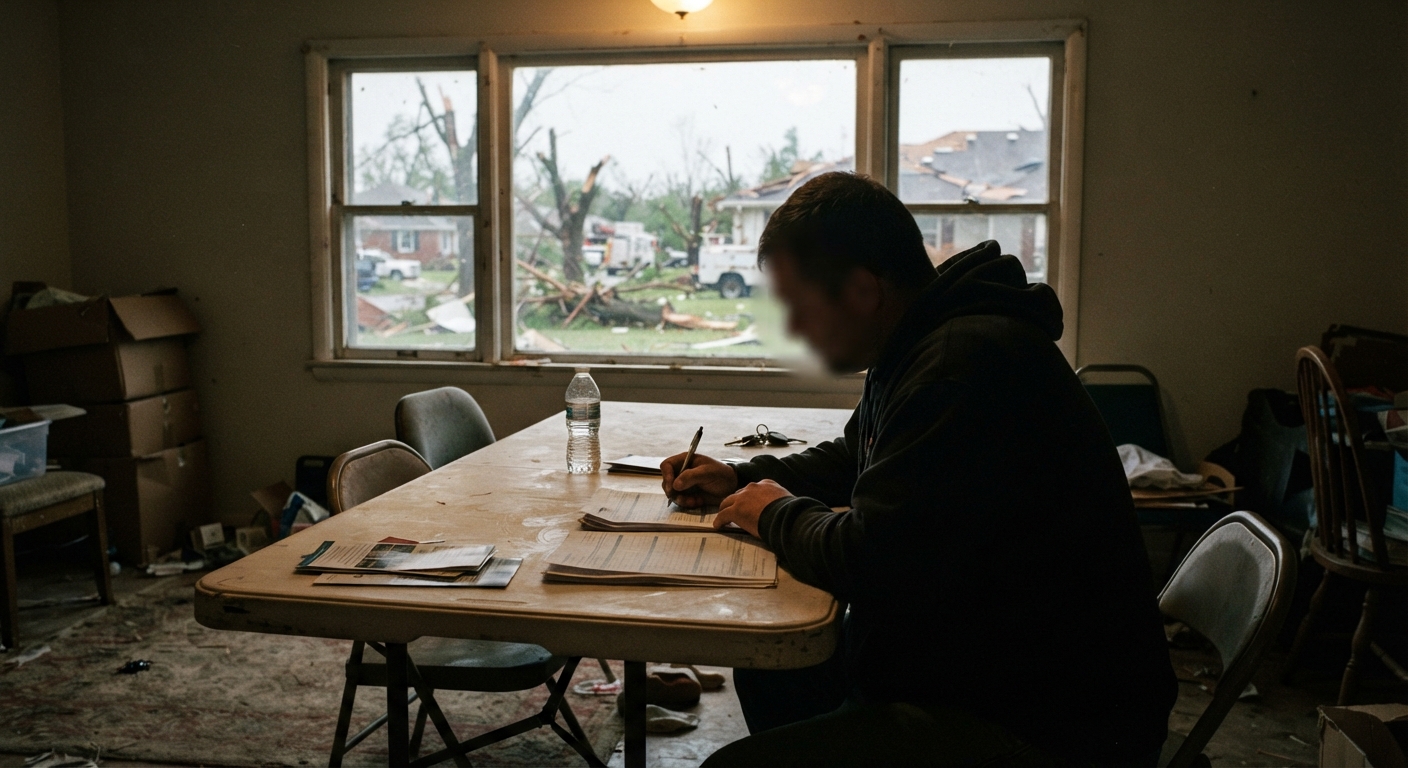
If the hurricane took your job along with your roof, or the wildfire closed the business you worked for, you may have already tried filing for unemployment and hit a wall. Regular state unemployment insurance wasn’t built for people whose jobs vanished because a disaster closed the doors, destroyed the workplace, or made it physically impossible to get to work. That’s where Disaster Unemployment Assistance comes in. It’s a separate federal program with its own rules, its own deadline, and its own definition of who counts as unemployed. Here’s what you need to know before that deadline passes.
What makes DUA different from standard unemployment insurance
Regular unemployment insurance is run by your state and funded by taxes employers pay on your wages. It exists for people who lost a job through layoffs, downsizing, or similar reasons, and it requires a minimum work history with an employer who paid into the system.
Disaster Unemployment Assistance is a federal program that only activates after a major disaster declaration includes individual assistance for unemployment. It’s designed to catch people who fall outside regular unemployment insurance entirely: the self-employed, gig workers, farmers, people who were about to start a job that no longer exists, and workers who exhausted their regular benefits but are still out of work because of the disaster. DUA is a backup net, not a replacement. If you qualify for regular unemployment insurance, you’re generally required to apply for that first, and DUA fills the gap if you don’t qualify or your regular benefits run out while you’re still affected by the disaster.
Who qualifies: employees, self-employed workers, and gig workers left without income after a declared disaster
DUA covers a wider range of work arrangements than regular unemployment. You may qualify if any of the following describes your situation after the disaster:
You worked for an employer whose business was damaged, destroyed, or closed because of the disaster. You’re self-employed and your business, farm, or workspace was damaged or you can’t access it. You were scheduled to start a job or self-employment that no longer exists because of the disaster. You can’t reach your job or place of self-employment because of storm damage, flooding, or road closures, even if the building itself is fine. You became the main income earner for your household because the head of household died as a result of the disaster. You can’t work because of an injury caused directly by the disaster.
In each case, the common thread is that the disaster itself, not a separate business decision or performance issue, is why you’re without income. Gig and contract workers who don’t normally qualify for regular unemployment insurance are exactly who this program is meant to catch.
The short filing window after a disaster declaration and why late applications get denied
This is the part people miss, and it’s the part that matters most. DUA has a strict filing deadline tied to the date the disaster declaration is announced, and it is measured in weeks, not months. Once that window closes, applications are generally denied regardless of how strong the underlying claim is, because the deadline is set by the terms of the disaster declaration itself, not by the caseworker reviewing your file.
The exact deadline is announced along with the disaster declaration and will be posted through your state’s unemployment agency. If you’re not sure whether the window is still open, don’t wait to find out through the mail. Call your state unemployment office directly or check its website the same day you realize you may qualify. If you’re a shelter worker or family member helping someone in crisis, treat this deadline the same way you’d treat a court date: find it, write it down, and file before it, even if some of the paperwork is still missing.
Documents you need: proof of employment or self-employment, proof you lived or worked in the disaster area
You can usually start a DUA claim before you have every document gathered, but the claim moves faster and is less likely to get stuck in review if you have these ready:
Proof of the work you lost, such as recent pay stubs, a letter from your employer, 1099 forms, invoices, contracts, or bank statements showing self-employment income. Proof you lived or worked in the area covered by the disaster declaration at the time it happened, such as a lease, utility bill, or mail addressed to that location. Identification showing who you are. If you were self-employed, anything showing you were operating the business before the disaster, even informal records like receipts or a business license.
If your workplace records were destroyed in the same disaster, say so on the application. Caseworkers handling DUA claims expect this problem and there are usually alternate ways to verify your situation, but you have to tell them the documents are gone rather than let the application sit incomplete.
How DUA payment amounts are calculated when your work history is incomplete or disaster-affected
DUA payments are based on your recent earnings, similar to regular unemployment insurance, but the calculation allows more flexibility when your records are thin or destroyed. If you’re missing pay stubs or tax documents because of the disaster, caseworkers can often use alternate proof, like bank deposit history or a signed statement, to estimate your typical earnings. Self-employed applicants without a full year of clean records won’t be denied outright for that reason alone.
If your normal documentation simply isn’t available yet, ask specifically whether a minimum or estimated benefit amount can be issued while you continue gathering paperwork. Don’t assume incomplete records mean you have to wait to file. File first, then work with your caseworker on filling in the numbers.
What to do if your disaster wasn’t federally declared but still cost you your job
DUA only exists where there’s a federal disaster declaration that specifically includes individual assistance for unemployment. If your fire, flood, or storm was serious to you but wasn’t declared at that level, or was declared for public assistance only, DUA may not be available at all.
That doesn’t mean you’re out of options. Apply for regular state unemployment insurance if you have any qualifying work history, since a disaster-related job loss can still count as a valid reason for separation depending on your state’s rules. Contact your state’s emergency management office to ask whether a declaration is pending or under review, since these determinations sometimes come through after initial damage assessments. And look into local and charitable emergency assistance funds, which often move faster than any government program and don’t require a federal declaration at all.
Combining DUA with other emergency disaster assistance without losing eligibility
You generally can receive DUA at the same time as other disaster aid, including one-time disaster relief payments, temporary housing assistance, and food assistance, since these programs serve different purposes and are usually not counted against each other. What you can’t do is collect DUA and regular unemployment insurance for the same week of unemployment, or receive DUA for a week you already earned full wages.
Report other disaster assistance honestly when asked, but don’t assume a housing grant or a food voucher will cancel out your unemployment claim. When in doubt, ask your unemployment caseworker directly which programs interact with DUA in your state, since some of these rules vary. The safest approach in the middle of a crisis is to apply for everything you might qualify for and let each agency sort out the overlap, rather than skipping a program because you’re worried it might conflict with another.